


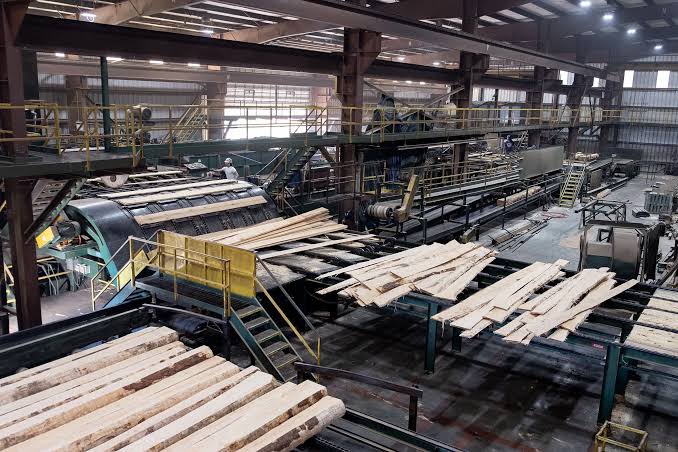
North America’s sawmill closures tell only one side of the capacity story. Since the beginning of 2025, a sizeable group of US mills has expanded, restarted, added shifts or moved through the final stages of major rebuilds, putting new lumber production into a market that is simultaneously losing capacity elsewhere.
The contrast is becoming sharper. Canada accounts for most of the large permanent closures and indefinite curtailments recorded over the past two years. In the United States, particularly across the South, capital continues to flow into larger and more productive mills.
Global Wood Markets Info (GWMI) has identified more than 20 sawmill projects that have added production, returned idled capacity or increased operating rates since early 2025.
 Thousands of quality articles
